Password or OTP?
The password and OTP screens looked too similar. Customers entered the wrong code and contacted support for help.
CASE STUDY 06 · FINTECH · ONBOARDING & CONVERSION
A ground-up redesign of Numida's onboarding experience — helping customers understand authentication, identifying business owners earlier, and making the path into the app more intentional.
THE CONTEXT · 01
A significant portion of people downloaded the Numida app without understanding that it was intended for registered and active businesses. The previous flow asked customers to verify their phone number and create a PIN before collecting business and personal details. This meant people who were not eligible could incur SMS verification costs before their business status was established. The onboarding flow lost 83.7% of users after phone verification. The Uganda Onboarding Overhaul set out to introduce eligibility messaging earlier, reorder onboarding steps and reduce wasted SMS spend.
These weren't issues we could understand from the interface alone. They surfaced through customer support, conversations with clients in the field and feedback from the sales acquisition team.
The password and OTP screens looked too similar. Customers entered the wrong code and contacted support for help.
People who didn't own a business could progress into the loan application, creating avoidable drop-offs and irrelevant applications.
OTP delivery was expensive. The redesign created an opportunity for the product team to move to a more cost-effective provider.
THE PRODUCT BRIEF · 02
The February 2026 PRD framed the problem around eligibility and wasted verification spend. Numida lends to registered and active businesses, but the previous flow asked people to verify their phone number before collecting their business name. That meant people who were not eligible could reach SMS verification before the product understood whether they were a business owner.
Drop-off after phone verification, when users were asked for their business name.
Of verified customers proceeded to enter their business name.
The PRD connected this drop-off to a second problem: high SMS verification costs per activated user, including spend on users who were not qualified for the product.
These are the PRD's baseline figures and targets. The impact review later reported its own baseline wording and actual results; those are shown separately in the outcomes section.
DISCOVERY · 02
We brought together signals from customer support, field conversations and the sales acquisition team. I partnered with another Product Designer to interview both existing and prospective clients — speaking to around six people.
Rather than map every possible issue in the product, we focused on the drop-off points that needed urgent attention. That helped us keep the work grounded in problems customers and internal teams were already experiencing.
Replace this panel with selected research artefacts or anonymised notes once the original materials are shared.
THE EXPERIENCE BEFORE & AFTER · 05
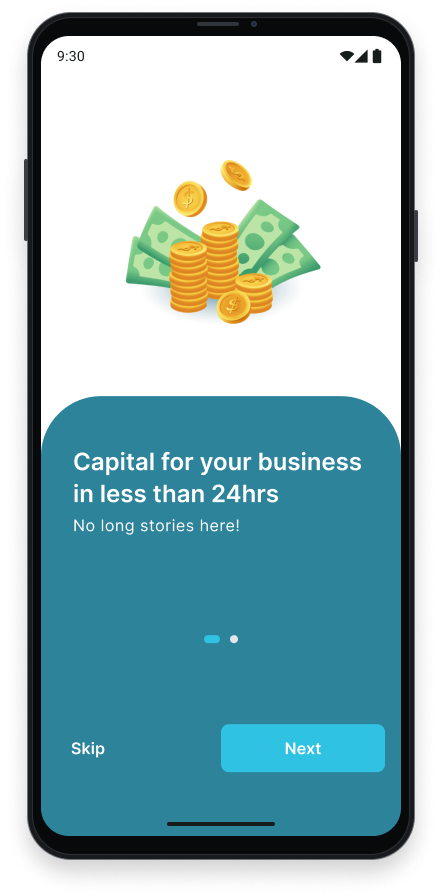
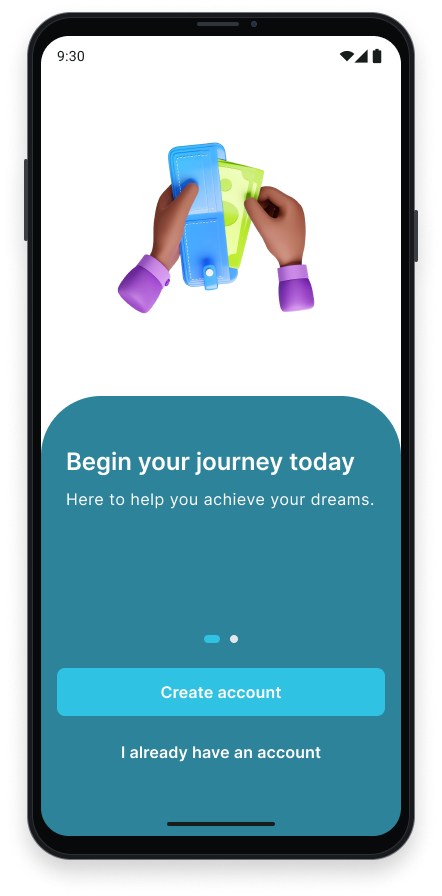
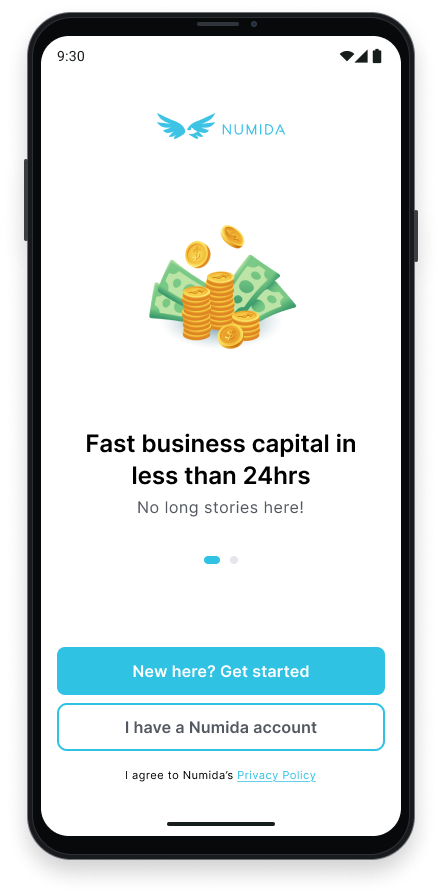
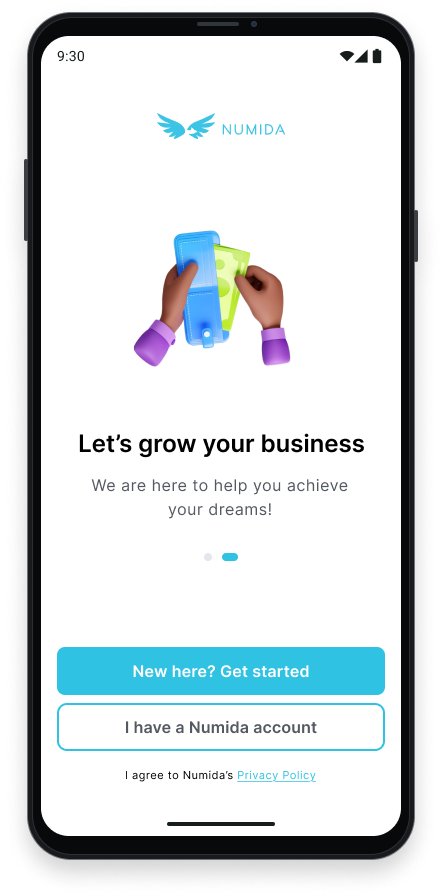
The previous flow moved from the onboarding carousel into phone verification and PIN creation, then asked for business and personal details. The redesigned flow brought business ownership and customer details forward, before phone verification and password setup.
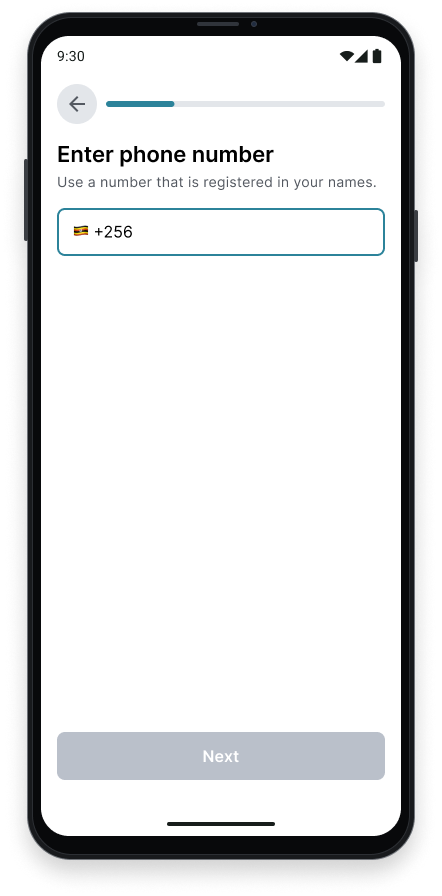
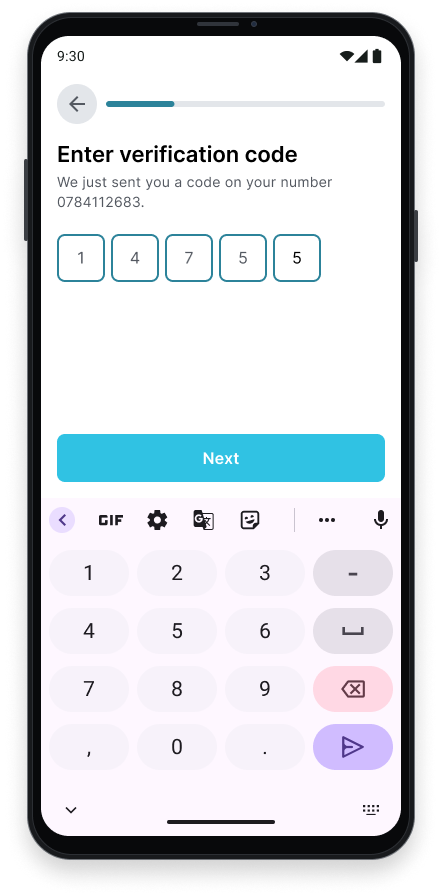
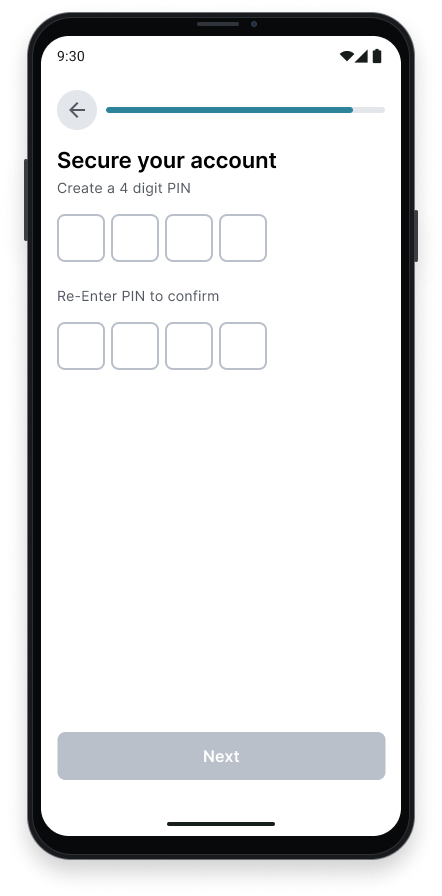
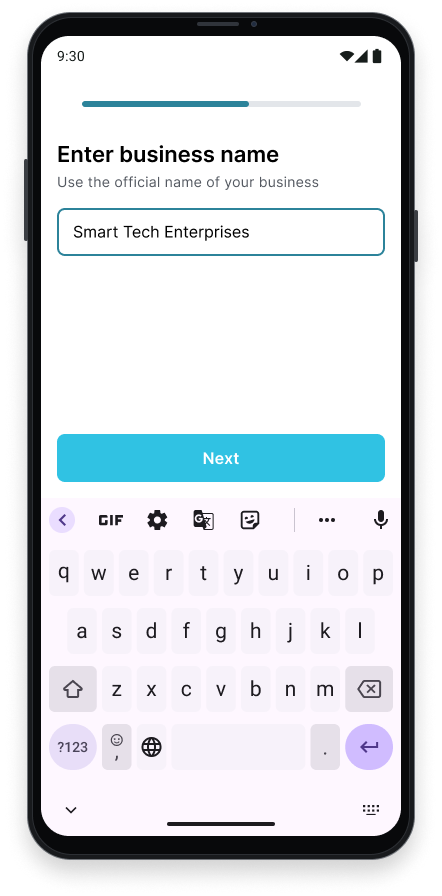
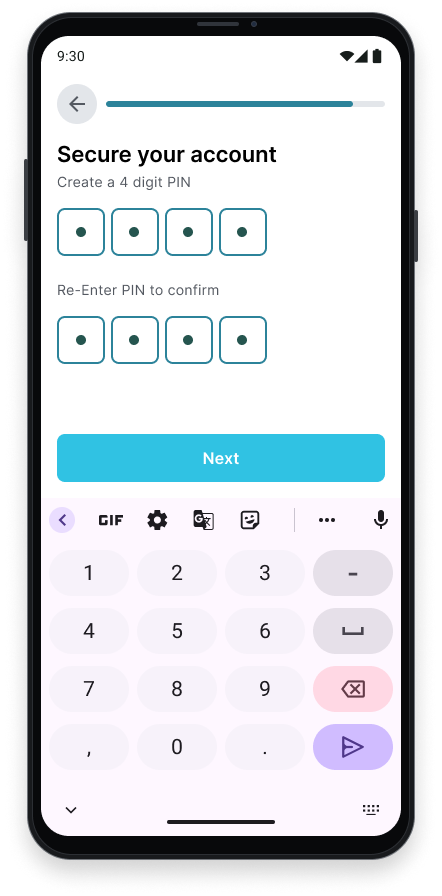
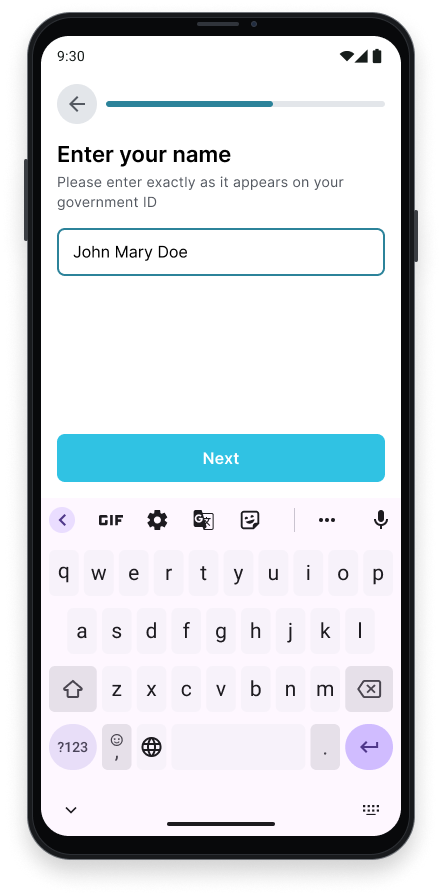
Customers reached SMS verification and PIN creation before the flow collected business and personal details.
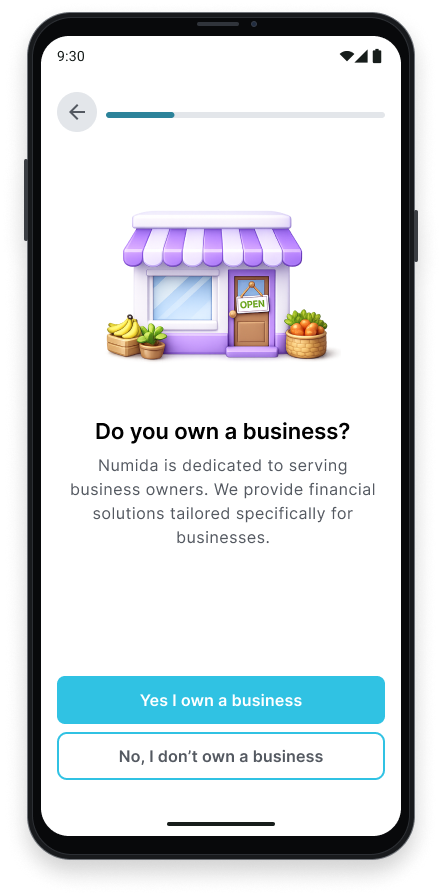
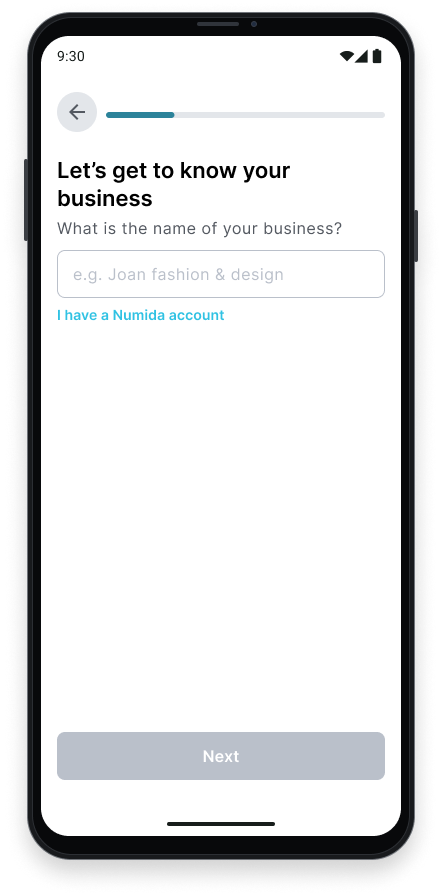
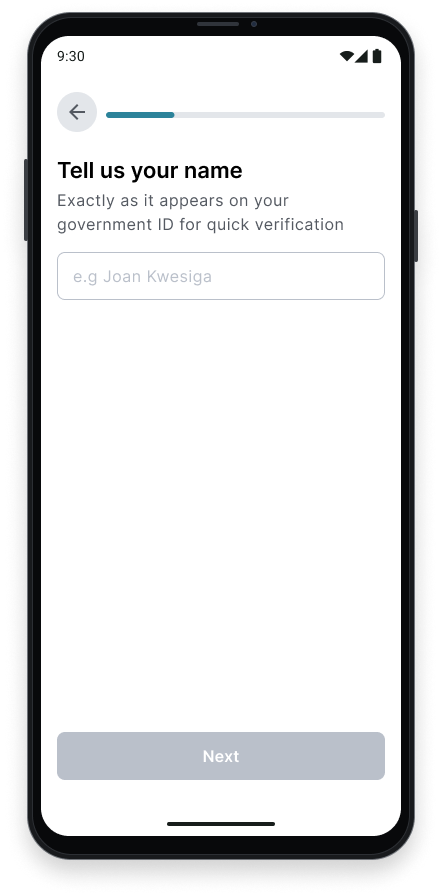
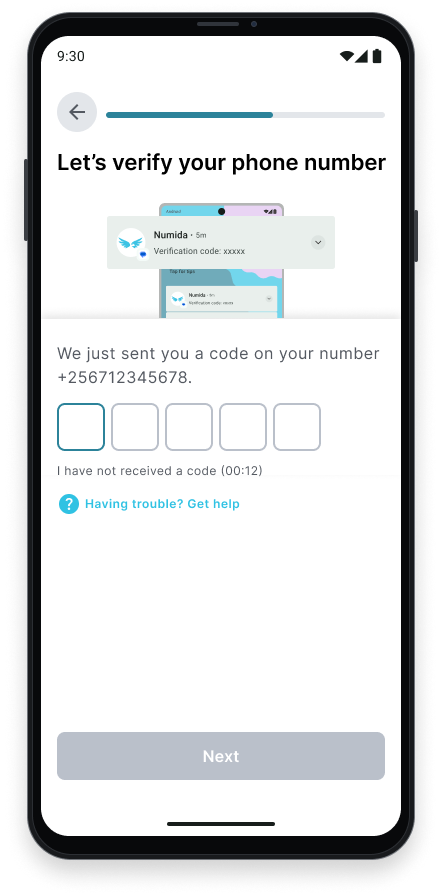
Business eligibility and details came before OTP verification, helping avoid verification spend on unqualified users.
THE PREVIOUS EXPERIENCE · SCREEN SEQUENCE
These original screens show the previous order: onboarding carousel, phone number, OTP, PIN creation and confirmation, then business and personal details, followed by completion.
THE PROPOSED APPROACH · 03
The PRD proposed three connected changes: make it clear from the beginning that Numida lends to registered and active businesses; collect the business name and personal name before phone number and OTP verification; and improve the PIN screen by renaming it “Password” while keeping the numeric input.
The PRD initially proposed comparing the existing flow with the updated flow through a prototype and A/B test. The team ultimately chose a direct production rollout instead. The expected cost impact of delaying the change was significant: continuing to verify unqualified users would mean continuing to incur avoidable SMS spend. The team therefore made a business decision to implement the redesigned flow without waiting for an experiment.
The final experience shown in this case study reflects the version released directly to production. The A/B test remained an initial proposal in the PRD; it was not the launch method.
DESIGN PRINCIPLES · 04
We treated this as a standalone, end-to-end onboarding redesign. The goal was to make the full journey more understandable while addressing the moments that were causing the most friction. In the shipped sequence, business ownership and customer details came before phone verification and the OTP screen.
THE NEW FLOW · SCREEN-BY-SCREEN
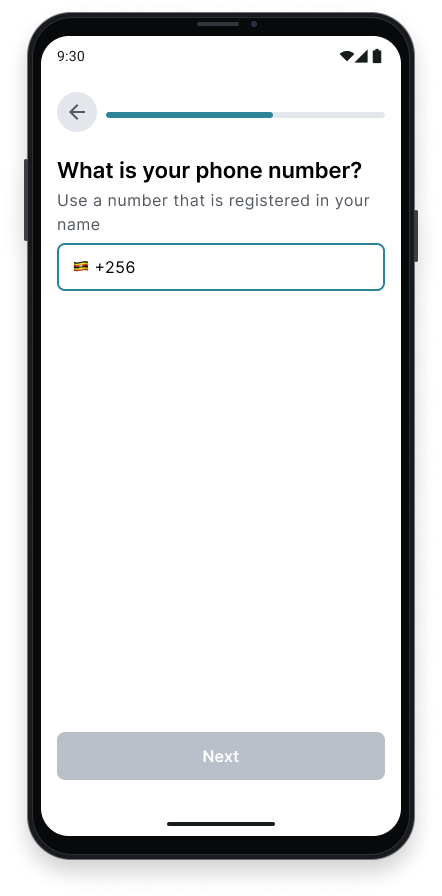
The redesigned journey introduced business eligibility and collected business and personal details before phone verification. These are the supplied final screen designs, shown in sequence.
DESIGN DECISION 01 · 06
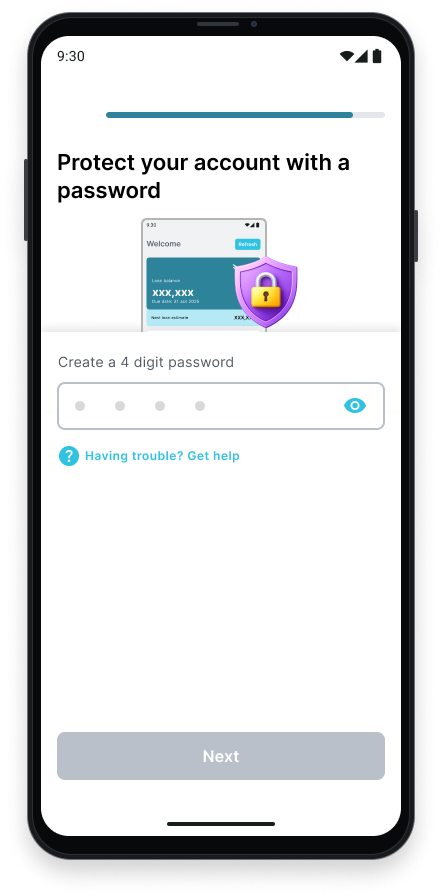
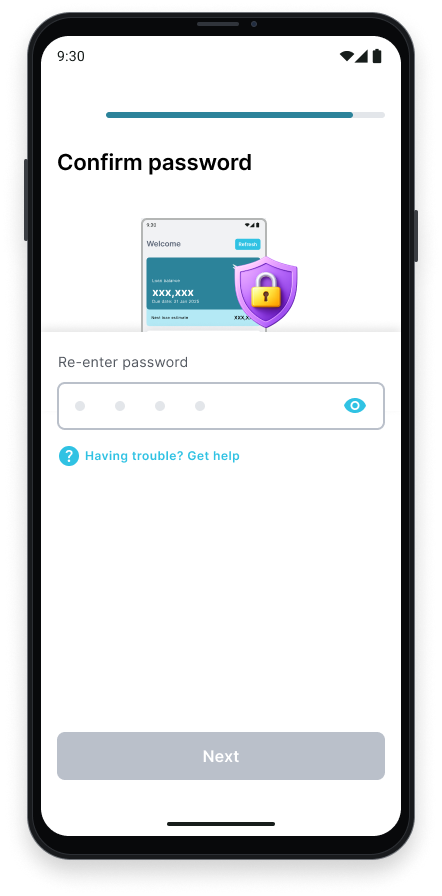
We redesigned both screens from scratch and deliberately moved away from the familiar pattern of using nearly identical layouts. We wanted the difference to be visible before someone had to read the instructions.
The verification code has its own distinct input treatment, visually different from the password field.
The PIN was renamed Password and presented in a single field for a four-digit code.
We also introduced images because our experience with Numida customers suggested they responded better to visual communication than text alone. The illustrations and distinct input structures helped make the two moments easier to tell apart.
The earlier OTP and PIN steps both relied on segmented code boxes, which contributed to customers confusing the two.
The redesigned screens gave OTP and Password different visual structures, supported by imagery and clearer naming.
WHAT WE TESTED · 07
We explored automatically populating the OTP when it arrived by SMS. It seemed like a convenient way to reduce effort, but in testing the code appeared so quickly that people weren't sure what had happened. They couldn't tell whether the app had responded, whether they needed to take an action or whether the process was complete.
We removed the automatic population. The lesson was that saving a tap only helps when the interface still gives people enough feedback to understand what's happening.
Participants moved through the flows easily and understood the distinction between “New users” and “I already have an account”.
Users paused at “Are you a business owner?”. This was interpreted as a positive signal that they were reading and considering the eligibility requirement before proceeding.
None of the six participants confused the verification code with the PIN. Users understood what each screen was asking them to do.
These are qualitative observations from six client-testing participants, not a statistically representative usability measure. Photos were not captured during the sessions.
DESIGN DECISION 02 · 08
We reordered the journey so customers confirmed business ownership and provided business and personal information before reaching the OTP screen. Customers who confirmed they owned a business could continue; those who did not were not taken further through the sign-up flow.
The intention was to qualify customers earlier, before they reached the loan application or triggered avoidable verification costs. It also reduced unqualified applications and incorrect details — what the team informally called “vibe applications”.
Once a customer confirmed they owned a business, the flow continued by collecting the business name, their name and phone number before OTP verification.
COLLABORATION & DELIVERY · 09
I led the design work from discovery through implementation, partnering with another Product Designer on client research. I sketched early ideas, developed the experience in Figma, and shared concepts with the Product Manager and engineering team for feedback. I also worked directly with engineers during implementation.
We involved the support team, loan officers and compliance alongside the Product Manager, Lead Frontend Engineer, Backend Engineer and Engineering Manager. Bringing Support into the process was especially valuable: once the team understood what was changing, they could prepare to explain the new experience and help customers through it.
Process reflection: We did not have a formal design QA stage after implementation. That's an area I'd build into the process next time, to check the shipped experience against the intended interaction.
THE OUTCOMES · 10
The impact update covered approximately 42,000 users across Uganda over a two-month analysis period. The project hypothesis was marked as confirmed.
Against a PRD target of 30% of verified users completing onboarding. The impact update recorded the result as “sooo on track”.
BASELINE CONTEXT: 80% drop-off after verification in the KPI table; the problem statement cites 83.7%.The impact update reports a 25% reduction. SMS spend was recorded as UGX 6 million in May and UGX 7 million in June, compared with a UGX 10 million baseline across January, February and March.
Target: 20%+ SMS cost reduction. All spend figures are in UGX.Renaming PIN to Password and redesigning the OTP screen made the difference clearer. Customers also saw earlier that Numida lends to businesses.
The reordered flow confirmed business ownership and collected business and personal information before OTP verification, helping reduce unqualified verified users.
Marketing had relied on business creation at the beginning of the old flow to identify customers who had not finished onboarding. The change affected that workflow and required better alignment across teams.
Eligibility was introduced before OTP verification, reducing SMS verification for users who were not qualified for the product.
WHAT THE LAUNCH TAUGHT US · 11
During launch, OTP failures made it look as though the redesign had broken verification. The underlying issue was an outage at the SMS provider, which had run low on wallet balance. The experience exposed a need for better observability of OTP failure rates and Slack alerts when provider outages or unusual failure rates occur.
We also learned that internal teams need to be prepared before a major market change goes live. Customer Support had not been fully briefed, and Marketing's existing follow-up process depended on business creation happening earlier in the journey. The reflection from the impact review was clear: involve Credit Ops and other affected teams before launch, and send a coming-soon message before the “it's live” update.
NEXT MARKETS · 12
The next step recorded in the impact update was to roll out the same flow in Rwanda, in Kinyarwanda. The team also identified a localisation issue: some Rwanda customers were seeing the Uganda onboarding when using a VPN or device settings that did not default to Rwanda. Engineering needed to address the app's market default.
Kenya was not planned as a simple copy of the Uganda flow. The team was exploring a different onboarding approach because it is a multi-product market.
WHAT I TOOK AWAY · 13
This project reinforced that onboarding doesn't end at the screen. The support team needs to understand what customers will see, why the experience changed and how to help when someone gets stuck. Involving them early made it easier to prepare for launch and support customers consistently.
It also reminded me to evaluate convenience through the customer's eyes. An automated action can be technically efficient and still feel confusing if the product doesn't communicate what just happened.